UK Couple Opens Pensions for Children as Young as Five Months
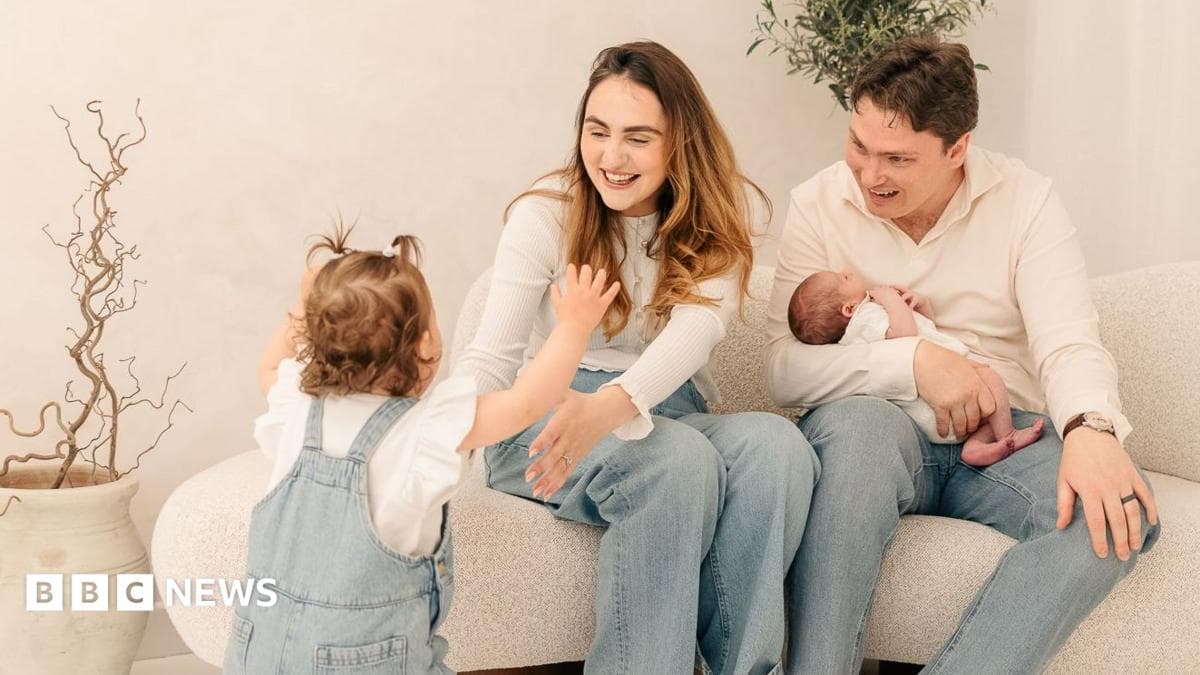
A couple in Swansea, UK, is making monthly contributions into Junior SIPPs (Self-Invested Personal Pensions) for their two children, aged 20 months and five months. With tax relief boosting their savings, the family is prioritizing long-term financial security, even though the children won’t access the funds until 2082 and 2083. The trend reflects growing interest in early financial planning for children, with similar schemes emerging in the US.

Editor, Lazyfounder
A couple in Swansea, UK, is making monthly contributions into Junior SIPPs (Self-Invested Personal Pensions) for their two children, aged 20 months and five months. With tax relief boosting their savings, the family is prioritizing long-term financial security, even though the children won’t access the funds until 2082 and 2083. The trend reflects growing interest in early financial planning for children, with similar schemes emerging in the US.
30 SEC SUMMARY
- A couple in Swansea, UK, is contributing £50 per month into Junior SIPPs (Self-Invested Personal Pensions) for their two young children, aged 20 months and five months.
- The UK government adds 20% tax relief to Junior SIPP contributions, boosting annual savings to £3,600 per child if the full £2,880 is contributed.
- Children in the UK cannot access private pension funds until age 57, meaning the Brain family’s children won’t benefit until 2082 and 2083.
- The US introduced a similar scheme, Trump Accounts, allowing up to $5,000 in annual contributions per child, accessible from age 18.
- Providers like Fidelity and Hargreaves Lansdown report a surge in Junior SIPP account openings, reflecting growing interest in long-term child savings.
TABLE OF CONTENTS
- Monthly Contributions and Long-Term Planning
- Tax Relief and Growth Potential
- Comparing UK and US Child Savings Schemes
- Reactions and Considerations
- What this means
- Key takeaways
- FAQ
- Sources
KEY HIGHLIGHTS
- Richard and Caitlin Brain, from Swansea, UK, are contributing £50 per month into Junior SIPPs for each of their two children, aged 20 months and five months.
- The UK government provides 20% tax relief on Junior SIPP contributions, adding up to £720 annually if the maximum £2,880 is contributed.
- Under current UK rules, children cannot access private pension funds until age 57, meaning the Brain children won’t benefit until 2082 and 2083.
- The Brains also save £60 per month into Junior ISAs for each child, which can be accessed at age 18.
- Junior SIPPs were introduced in the UK in 2001, and providers like Fidelity and Hargreaves Lansdown report a significant increase in account openings.
- US President Donald Trump launched Trump Accounts in July 2026, allowing up to $5,000 in annual contributions per child, accessible from age 18.
Monthly Contributions and Long-Term Planning
Richard and Caitlin Brain, a couple from Swansea, UK, are contributing £50 per month into Junior SIPPs (Self-Invested Personal Pensions) for each of their two children, aged 20 months and five months. The couple also saves £60 per month into Junior ISAs for each child, aiming to provide financial support for both near-term and long-term needs.
Under current UK rules, the children will not be able to access the pension funds until they turn 57. This means the eldest child will wait until 2082, while the youngest will have to wait until 2083.
The Brains, who earn less than £90,000 annually, are making financial sacrifices to support their children’s future. Their combined monthly contributions to their children’s funds total £220, in addition to £200 they save toward their own pensions and savings.
Tax Relief and Growth Potential
The UK government provides 20% tax relief on Junior SIPP contributions, meaning every £2,880 contributed annually is topped up to £3,600. This incentive has made Junior SIPPs an attractive option for parents looking to maximize long-term savings for their children.
According to projections, contributing £50 per month into a Junior SIPP from birth—boosted by tax relief—could grow to approximately £135,000 by the time the child reaches retirement age. This assumes steady investment growth over the decades.
Junior SIPPs were introduced in the UK in 2001, and their popularity has surged in recent years. Providers like Fidelity and Hargreaves Lansdown report that the number of Junior SIPP accounts has more than tripled since December 2023.
Comparing UK and US Child Savings Schemes
While the UK offers Junior SIPPs, the US introduced a similar scheme in July 2026 called Trump Accounts. These allow contributions of up to $5,000 (£3,800) per year per child, with funds accessible from age 18. However, early withdrawals may incur taxes and a 10% penalty.
Wally Luckeydoo, a personal finance teacher in Tennessee, has opened Trump Accounts for his two children, aged four and three. He sees the scheme as a way to provide financial security for their future education or other needs.
Unlike Junior SIPPs, Trump Accounts offer earlier access to funds, though with different tax implications. This flexibility may appeal to families who prioritize near-term financial goals alongside long-term savings.
Reactions and Considerations
Hugo Thompson, a 15-year-old whose parents have contributed to his Junior SIPP, is unbothered by the long wait to access the funds. He views the savings as a helpful foundation for his future, even if it won’t be available until he is 57.
Jemma Slingo, a pensions specialist at Fidelity, notes that Junior SIPPs are gaining traction among parents who want to give their children a financial head start. However, she emphasizes the importance of balancing child savings with other financial priorities, such as retirement planning and emergency funds.
What this means
Lazyfounder analysis — our interpretation, not reported fact.
For founders and operators, the growing interest in Junior SIPPs and similar schemes highlights a broader trend: parents are increasingly thinking decades ahead when it comes to financial planning. The tax advantages and long-term growth potential of these products make them compelling, but the trade-off is illiquidity—funds are locked away for decades.
This trend could inspire new financial products or services that balance long-term growth with flexibility. For example, hybrid savings tools that combine the benefits of tax relief with earlier access to funds—similar to the US Trump Accounts—might appeal to parents who want both security and liquidity.
Additionally, the rise of child-focused savings schemes underscores the need for financial education targeting younger audiences. If teenagers like Hugo Thompson are already engaging with long-term savings, there’s an opportunity to create tools or platforms that help them—and their parents—navigate these decisions with confidence.
Key takeaways
- Starting a pension for children early can significantly benefit from compound growth and tax relief over decades.
- UK Junior SIPPs offer tax advantages but lock funds until age 57, making them a long-term commitment.
- Junior ISAs provide a more flexible alternative for near-term financial needs, as funds can be accessed at age 18.
- The popularity of Junior SIPPs is rising, with providers reporting increased adoption among parents and guardians.
- US Trump Accounts offer a similar savings option but with earlier access and different tax implications compared to UK Junior SIPPs.
FAQ
What is a Junior SIPP?
A Junior SIPP (Self-Invested Personal Pension) is a UK pension scheme designed for children. Parents or guardians can contribute up to £2,880 annually, which the government tops up with 20% tax relief, making the total £3,600 per year. The funds are locked until the child turns 57 under current rules.
How do Trump Accounts differ from Junior SIPPs?
Trump Accounts are a US-based retirement savings scheme for children, allowing contributions of up to $5,000 per year. Unlike Junior SIPPs, funds in Trump Accounts can be accessed from age 18, though early withdrawals may incur taxes and penalties.
Why are parents opening pensions for young children?
Parents are leveraging tax relief and long-term growth potential to provide financial security for their children. By starting early, even small contributions can grow significantly over decades, offering a head start for retirement or other future expenses.
What are the risks of locking funds in a Junior SIPP until age 57?
The primary risk is illiquidity—children cannot access the funds until they turn 57. This means the money is unavailable for near-term needs like education or housing. Parents must balance long-term savings with more flexible financial tools like Junior ISAs.
Are Junior SIPPs becoming more popular?
Yes. Providers like Fidelity and Hargreaves Lansdown report that the number of Junior SIPP accounts has more than tripled since December 2023, reflecting growing interest among parents in long-term financial planning for their children.
Related on Lazyfounder
Sources
- BBC News (Tech & Business) · 2026-10-05
We're saving £100 a month into pensions for our toddler and baby - here's why - BBC News (Tech & Business) · 2026-10-05
Toddler pensions: Why we're saving £100 a month for our kids - BBC News (Tech & Business) · 2026-10-05
Toddler pensions: Why we're saving £100 a month for our kids
This story is an original summary drafted with AI by Lazyfounder from the reporting listed above and checked by automated validation. Facts are attributed to their original publishers; sections marked as analysis are Lazyfounder's. Where a source is in another language, facts were machine-translated and quotations are reported, not reproduced. Read the original coverage via the links, and see our AI policy and corrections policy.
About the author
Editor, Lazyfounder
Tarun Mottlia edits LazyFounders, covering Indian startups, funding rounds, AI and product launches. Every story on the site is AI-assisted and checked against its cited sources before publication.
More stories by Tarun MottliaGet the LazyFounder Brief
Startup, funding and AI news in a five-minute read. Join the early-access list.