UK mortgage rates hit 6% for first time in three years
The UK mortgage market is facing a sharp rise in borrowing costs, with the average five-year fixed mortgage rate reaching 6% for the first time in three years. Major lenders have withdrawn thousands of lower-rate deals and raised rates repeatedly, squeezing homebuyers amid economic uncertainty and global pressures.

Editor, Lazyfounder
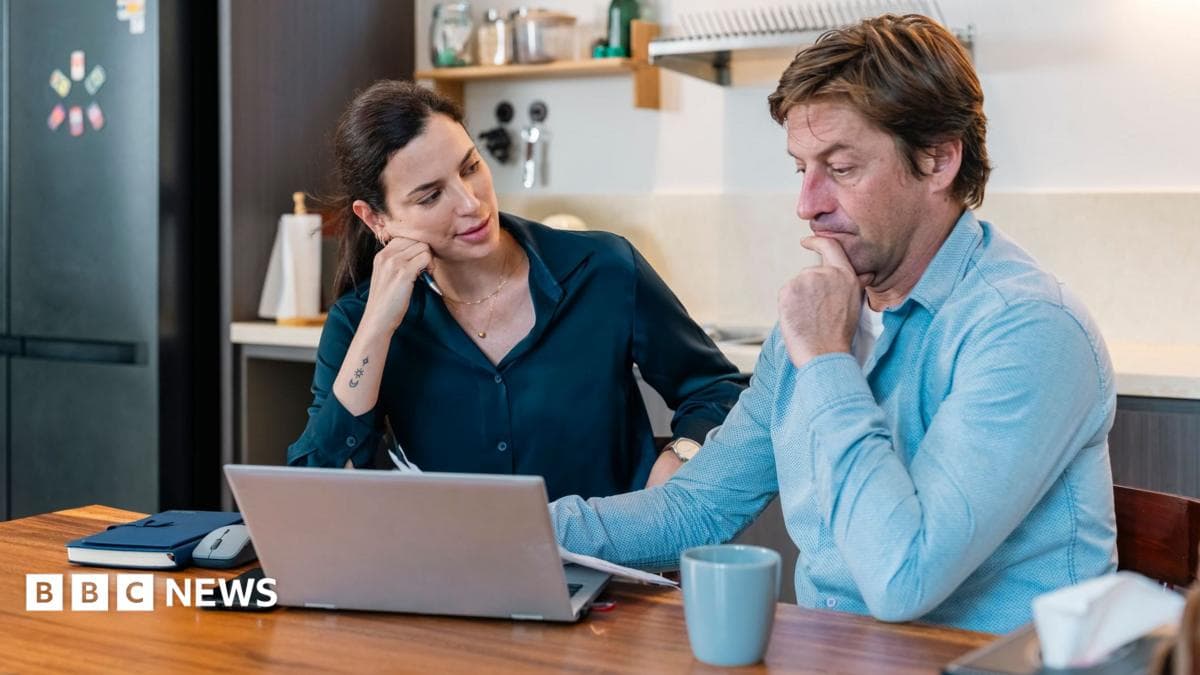
The UK mortgage market is facing a sharp rise in borrowing costs, with the average five-year fixed mortgage rate reaching 6% for the first time in three years. Major lenders have withdrawn thousands of lower-rate deals and raised rates repeatedly, squeezing homebuyers amid economic uncertainty and global pressures.
30 SEC SUMMARY
- The average five-year fixed mortgage rate in the UK has hit 6% for the first time in three years.
- Around 1,500 mortgage deals priced below 5% have disappeared since the start of September.
- Major UK lenders, including Barclays, HSBC, and Nationwide, have raised fixed mortgage rates multiple times in September.
- Economic uncertainty and rising interest rates are driving up borrowing costs for homebuyers.
- The average two-year fixed mortgage rate is now 5.98%, the highest since December 2023.
TABLE OF CONTENTS
- Mortgage rates surge to three-year high
- Lower-rate deals vanish as costs rise
- Lenders raise rates amid economic pressures
- Economic uncertainty drives borrowing costs
- Context for borrowers and innovators
- What this means
- Key takeaways
- FAQ
- Sources
KEY HIGHLIGHTS
- The average five-year fixed mortgage rate in the UK has reached 6%, the first time since 2023.
- Around 1,500 mortgage deals priced below 5% have disappeared since the start of September.
- Major lenders, including Barclays, HSBC, and Nationwide, have raised fixed mortgage rates multiple times in September.
- Economic uncertainty and rising interest rates are driving up the cost of borrowing for homebuyers.
- The average two-year fixed mortgage rate is now 5.98%, its highest level since December 2023.
Mortgage rates surge to three-year high
The average interest rate on a new five-year fixed mortgage deal in the UK has reached 6% for the first time in three years, according to BBC News. This marks a significant shift in the housing market, driven by rising borrowing costs and broader economic uncertainty.
Lower-rate deals vanish as costs rise
The average two-year fixed mortgage rate has also climbed, now standing at 5.98%. This is the highest level recorded since December 2023, reflecting a rapid escalation in borrowing costs for homebuyers.
Since the beginning of September, around 1,500 mortgage deals priced below 5% have been withdrawn from the market. This reduction in lower-cost options has tightened the availability of affordable home loans, putting further pressure on buyers.
Lenders raise rates amid economic pressures
Major UK lenders have responded to economic pressures by raising fixed mortgage rates multiple times in September. Barclays increased selected fixed rates on four occasions, while HSBC, Lloyds Bank, Nationwide, NatWest, Santander, and TSB each implemented three rounds of rate hikes during the month.
According to data provider Moneyfacts, the situation has become "brutal" for borrowers, as lenders adjust to higher funding costs and a more uncertain economic outlook.
Economic uncertainty drives borrowing costs
The increase in mortgage rates is tied to broader economic factors, including rising inflation, higher interest rates, and increased government borrowing costs. Global economic uncertainty, exacerbated by geopolitical tensions such as the conflict involving Iran, has also contributed to the rise in home loan costs.
Fixed-rate mortgages, which account for the vast majority of home loans in the UK, lock borrowers into a set rate for a period—typically two or five years. The recent surge in rates means higher monthly repayments for new borrowers and those remortgaging.
Context for borrowers and innovators
First-time homebuyers in the UK have faced significant financial hurdles in recent years, with rising property prices and now higher mortgage rates adding to the challenge. Many rely on government schemes or low-deposit mortgage options to enter the market, but the disappearance of lower-rate deals could further stretch affordability.
Recent innovations in the financial sector, such as tokenised deposits, aim to modernise banking infrastructure. However, these developments are unlikely to provide immediate relief to borrowers grappling with higher mortgage costs.
What this means
Lazyfounder analysis — our interpretation, not reported fact.
For UK founders and operators in the real estate and fintech sectors, this surge in mortgage rates is a clear signal of tightening financial conditions. Startups offering mortgage brokering, financial planning, or alternative lending solutions may see increased demand as buyers seek ways to navigate higher borrowing costs. However, the disappearance of lower-rate deals could also reduce the pool of potential homebuyers, slowing transaction volumes and impacting proptech platforms reliant on market activity.
The broader economic uncertainty—driven by factors like inflation and geopolitical tensions—suggests that volatility may persist. Founders should prepare for a period of cautious consumer spending, particularly in high-ticket sectors like housing. For those building tools for lenders or borrowers, now is the time to emphasize flexibility, transparency, and cost-saving features to stand out in a challenging market.
Key takeaways
- UK mortgage rates have risen sharply, with the average five-year fixed rate reaching 6% for the first time in three years.
- Over 1,500 mortgage deals priced below 5% have been withdrawn since September, reducing options for borrowers.
- Major lenders like Barclays, HSBC, and Nationwide have increased fixed rates multiple times in September.
- Economic uncertainty and global factors, including inflation and geopolitical tensions, are driving the rise in borrowing costs.
- The average two-year fixed mortgage rate is now 5.98%, the highest since December 2023.
FAQ
Why have UK mortgage rates risen to 6%?
The rise in mortgage rates is driven by economic uncertainty, including inflation, higher interest rates, and increased government borrowing costs. Global factors, such as geopolitical tensions, have also contributed to the surge.
How are lenders responding to the rise in mortgage rates?
Major UK lenders, including Barclays, HSBC, and Nationwide, have raised fixed mortgage rates multiple times in September. Many have also withdrawn lower-rate mortgage deals, reducing options for borrowers.
What does this mean for first-time homebuyers?
First-time buyers are facing higher borrowing costs and fewer affordable mortgage options. The disappearance of deals priced below 5% and the rise in rates could make it harder to save for deposits and secure loans.
Are fixed-rate mortgages still the most common option in the UK?
Yes, the vast majority of homebuyers in the UK opt for fixed-rate mortgages, which lock in a set rate for a period—usually two or five years.
Related on Lazyfounder
Sources
- BBC News (Tech & Business) · 2026-10-05
Average five-year mortgage rate hits 6% for first time in three years - BBC News (Tech & Business) · 2026-10-05
Average five-year mortgage rate hits 6% for first time in three years
This story is an original summary drafted with AI by Lazyfounder from the reporting listed above and checked by automated validation. Facts are attributed to their original publishers; sections marked as analysis are Lazyfounder's. Where a source is in another language, facts were machine-translated and quotations are reported, not reproduced. Read the original coverage via the links, and see our AI policy and corrections policy.
About the author
Editor, Lazyfounder
Tarun Mottlia edits LazyFounders, covering Indian startups, funding rounds, AI and product launches. Every story on the site is AI-assisted and checked against its cited sources before publication.
More stories by Tarun MottliaGet the LazyFounder Brief
Startup, funding and AI news in a five-minute read. Join the early-access list.