
UK regulators warn of unregulated debt firms exploiting consumers
The UK’s Financial Conduct Authority (FCA) has raised alarms about unregulated firms offering debt advice that may mislead consumers into fee-charging solutions. These firms often use cold calling and impersonation tactics, leaving individuals with higher financial burdens and fewer options.

Editor, Lazyfounder
30 SEC SUMMARY
- The UK’s Financial Conduct Authority (FCA) warns consumers about unregulated firms offering debt advice.
- These firms often use cold calling, online ads, or impersonation to collect personal details.
- Victims are pressured into fee-charging debt solutions without being told about free alternatives.
- StepChange advises seeking free, impartial debt advice before making financial decisions.
TABLE OF CONTENTS
KEY HIGHLIGHTS
- Unregulated firms in the UK are targeting consumers through cold calling and online advertisements.
- Some firms impersonate debt advice charities or debt collectors to extract personal information.
- Victims report being pressured into paid debt solutions like Individual Voluntary Arrangements (IVAs) without being informed of free alternatives.
- The FCA highlights warning signs, including repeated contact and coaching on how to respond to lenders.
FCA warns of unregulated debt advice firms
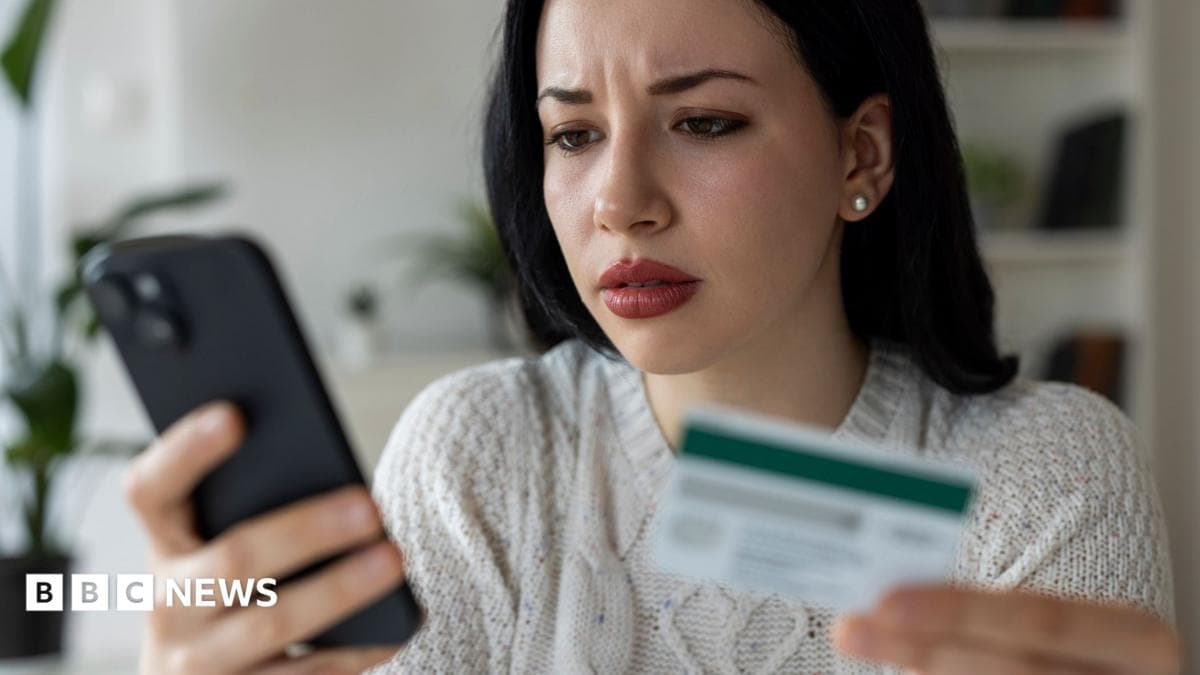
The UK’s Financial Conduct Authority (FCA) has issued a warning about unregulated firms offering debt advice that may exploit consumers in financial distress. According to BBC News, these firms often use cold calling, online advertisements, or impersonation tactics to collect personal details, which are then used to promote fee-charging debt solutions.
The FCA reports that some unregulated firms impersonate legitimate debt advice charities or debt collectors, misleading consumers into sharing sensitive information. Once obtained, these details are frequently passed to firms offering paid services, such as Individual Voluntary Arrangements (IVAs) or debt management plans, without explaining free alternatives.
Pressure tactics and misleading practices
Consumers have reported being subjected to pressure tactics, including repeated contact from these firms. According to BBC News, some individuals were coached on how to respond to lenders or encouraged to alter financial details on lenders’ paperwork,actions that could worsen their financial situation.
The FCA has identified warning signs of unscrupulous firms, such as aggressive communication, lack of transparency about fees, and failure to disclose free debt advice options. These practices can leave consumers with higher financial obligations and fewer resources to manage their debt.
Call for free, impartial debt advice
Vikki Brownridge, chief executive of the debt charity StepChange, emphasized the importance of seeking free and impartial advice before committing to any debt solution. She advised consumers to verify the legitimacy of firms offering debt advice and to explore regulated, non-profit alternatives.
The FCA’s warning serves as a reminder for consumers to exercise caution when approached by firms offering debt-related services, particularly those that charge fees upfront or use high-pressure tactics.
What this means
Lazyfounder analysis — our interpretation, not reported fact.
This warning from the FCA underscores the risks of unregulated financial services, particularly for vulnerable consumers. For founders and operators in the debt advice or fintech space, it’s a reminder that ethical practices aren’t just a regulatory requirement—they’re a competitive advantage. Firms that prioritize transparency and consumer protection are more likely to build long-term trust, while those cutting corners risk reputational damage and regulatory action. The rise of fee-charging debt solutions also highlights an opportunity for startups to differentiate by offering free, impartial advice—aligning profit with social impact.
Key takeaways
- Founders in fintech or debt management must ensure compliance with regulations to avoid exploitative practices.
- Operators should prioritize transparency when offering paid debt solutions, clearly explaining free alternatives.
- Consumer trust is critical—unregulated or aggressive tactics can damage reputation and lead to regulatory scrutiny.
- Free debt advice services like StepChange can serve as a model for ethical financial guidance.
FAQ
What are the warning signs of an unregulated debt advice firm?
Warning signs include repeated or aggressive contact, pressure to pay for debt solutions, lack of transparency about fees, and failure to inform consumers about free alternatives. Some firms may also impersonate legitimate charities or debt collectors.
What should consumers do if they need debt advice?
Consumers are advised to seek free and impartial debt advice from regulated organizations, such as StepChange, before making any financial decisions. It’s important to verify the legitimacy of any firm offering debt services.
What are Individual Voluntary Arrangements (IVAs)?
IVAs are fee-charging debt solutions that allow individuals to pay off their debts over a set period. However, they are not the only option, and consumers should explore free alternatives before committing to paid services.
Related on Lazyfounder
Sources
- BBC News (Tech & Business) · 2026-10-11
Debt advice that may leave you owing even more money
This story is an original summary drafted with AI by Lazyfounder from the reporting listed above and checked by automated validation. Facts are attributed to their original publishers; sections marked as analysis are Lazyfounder's. Where a source is in another language, facts were machine-translated and quotations are reported, not reproduced. Read the original coverage via the links, and see our AI policy and corrections policy.
About the author
Editor, Lazyfounder
Tarun Mottlia edits LazyFounders, covering Indian startups, funding rounds, AI and product launches. Every story on the site is AI-assisted and checked against its cited sources before publication.
More stories by Tarun MottliaGet the LazyFounder Brief
Startup, funding and AI news in a five-minute read. Join the early-access list.
