Mukuru expands remittance-led neobank model to bridge cash and digital spending
Mukuru, a South Africa-based digital financial services company, is expanding its remittance-led neobank model to bridge the gap between receiving and spending money. With operations in over 60 countries and 17.6 million customers, the company is transitioning from cross-border remittances to everyday financial services, including wallets, cards, and payments.

Editor, Lazyfounder
30 SEC SUMMARY
- Mukuru, a South Africa-based digital financial services company, is expanding its remittance-led neobank model to over 60 countries, serving 17.6 million customers.
- The company is transitioning from cross-border remittances to everyday financial services like wallets, cards, and payments.
- Mukuru recently launched a physical Visa debit card in Botswana, linked to its wallet, in partnership with Bank Zero.
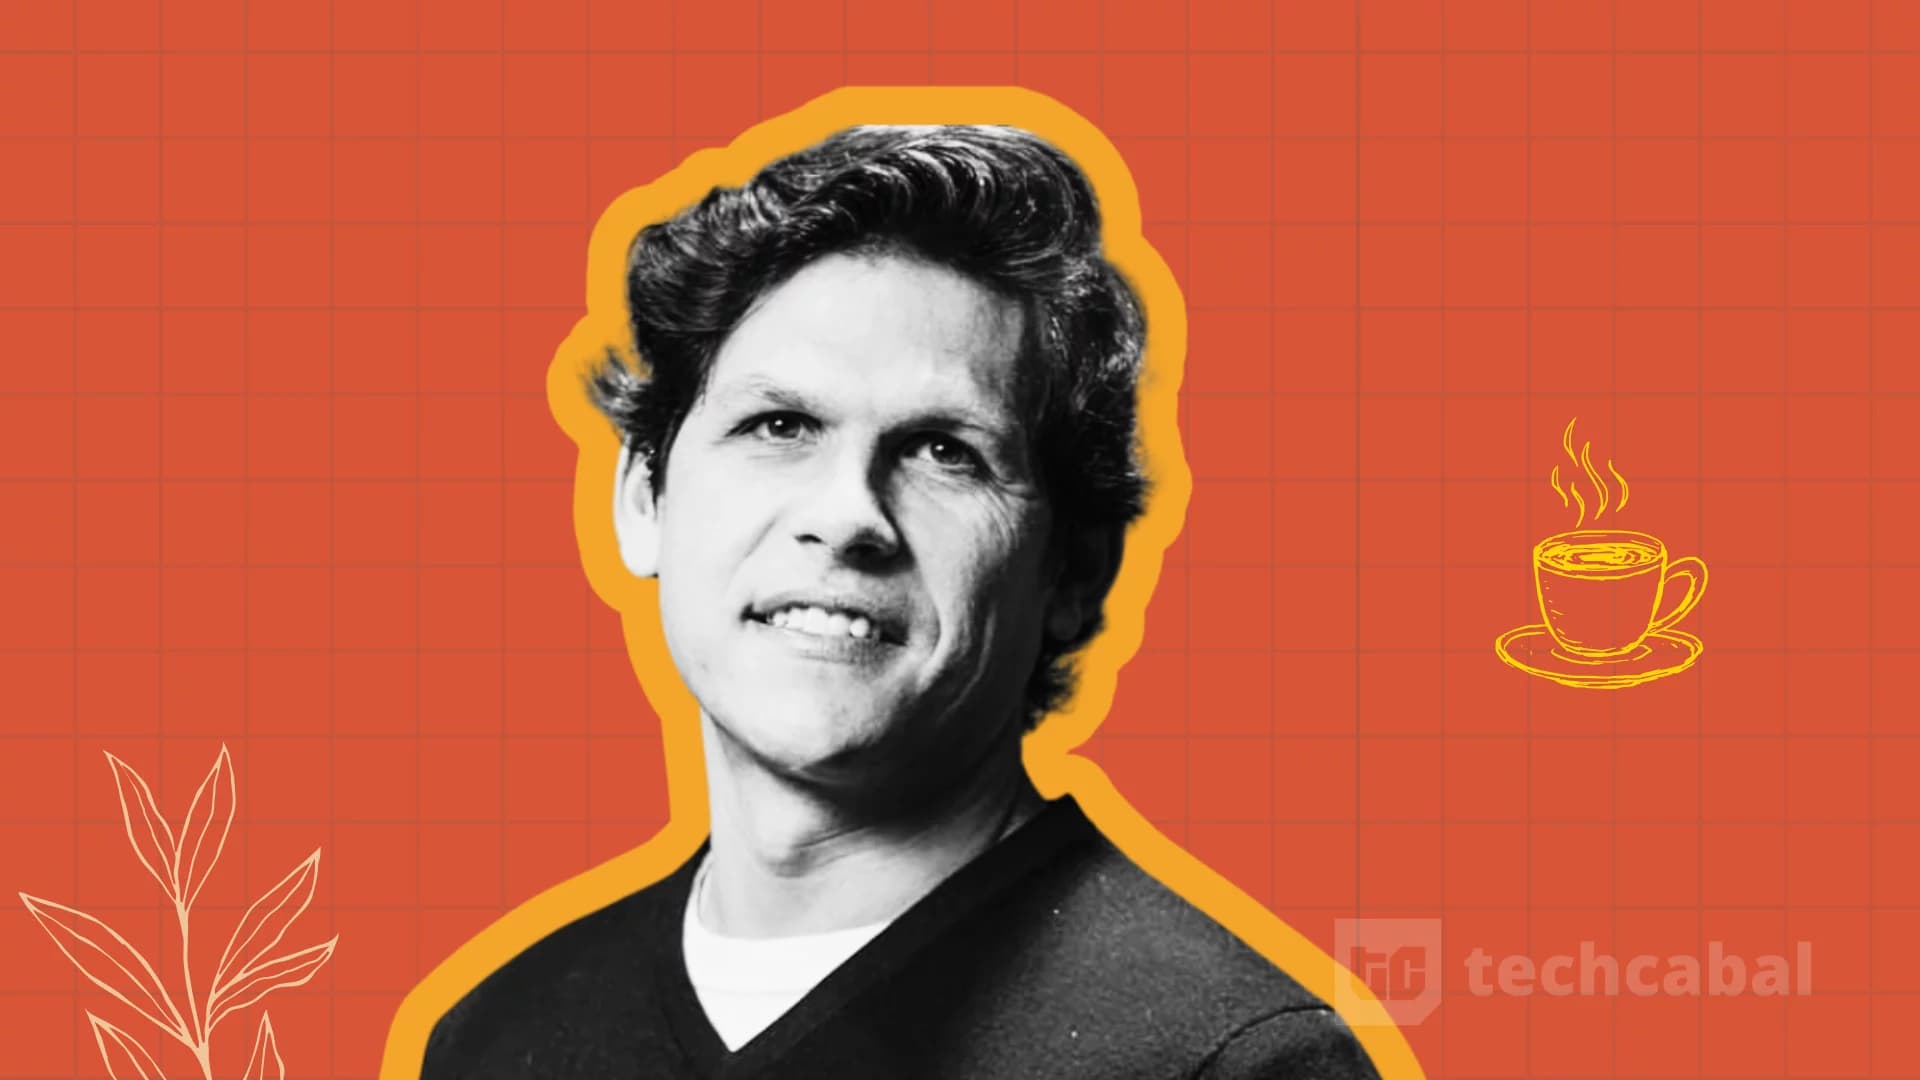
- Juan Seco, Chief Growth Officer and Managing Director for East Africa, leads Mukuru’s expansion strategy to reduce friction in financial transactions.
- Mukuru’s approach focuses on integrating services into customers’ existing money management habits, including USSD, WhatsApp bots, and agent networks.
TABLE OF CONTENTS
KEY HIGHLIGHTS
- Mukuru operates in over 60 countries and serves 17.6 million customers.
- The company launched a physical Visa debit card in Botswana, linked to its wallet.
- Mukuru partnered with Bank Zero to provide banking infrastructure for its account and card offerings, migrating 500,000 customers.
- Juan Seco joined Mukuru in 2023 as Chief Growth Officer and Managing Director for East Africa.
- Mukuru’s expansion is designed to fit into customers’ existing financial habits, including USSD, WhatsApp bots, and agent networks.
Mukuru’s expansion into neobanking
According to TechCabal, Mukuru is expanding its remittance-led neobank model to provide seamless financial services across over 60 countries. The company, headquartered in South Africa, serves 17.6 million customers and has spent two decades facilitating cross-border money transfers.
Mukuru’s strategy focuses on eliminating friction in financial transactions, particularly for customers in Southern and East Africa. Juan Seco, Chief Growth Officer and Managing Director for East Africa, describes the company as a "remittance-led neobank," emphasizing its shift from traditional remittances to broader digital financial services.
New card offering and banking partnership
In Botswana, Mukuru recently launched a physical Visa debit card linked to its wallet. This move is part of a broader push to integrate remittance recipients into the formal financial system, allowing them to receive salaries, make electronic payments, and use cards for everyday transactions.
Mukuru has partnered with Bank Zero, a South African bank, to provide the infrastructure for its account and card offerings. Approximately 500,000 Mukuru customers are being migrated to Bank Zero’s platform, which already supports over 700,000 end users.
Leadership and customer-centric strategy
Juan Seco joined Mukuru in 2023 after serving as Chief Financial Officer (CFO) at Jumia, where he took a pay cut to relocate to Nairobi. At Jumia, he helped launch JumiaPay to address gaps in mobile-money interoperability across markets like Egypt, Nigeria, and Kenya.
Seco’s approach at Mukuru mirrors this focus on reducing friction. He emphasizes that the company’s expansion is not about selling more products but about embedding services into how customers already manage their money. This includes offering multiple access points, such as USSD, WhatsApp bots, and agent networks.
What this means
Lazyfounder analysis — our interpretation, not reported fact.
Mukuru’s expansion reflects a growing trend in emerging markets: leveraging remittance networks as a foundation for broader financial inclusion. For founders, this model shows how addressing a specific pain point—like cross-border transactions—can create trust and open doors to adjacent services like wallets and cards. The partnership with Bank Zero also highlights how fintechs can collaborate with regulated entities to accelerate compliance and scale. Operators should note Mukuru’s customer-centric approach: instead of pushing new products, it integrates services into existing behaviors, whether through USSD, WhatsApp, or agent networks. This strategy could be particularly effective in regions where digital literacy varies widely.
Key takeaways
- Fintech companies in emerging markets can drive adoption by reducing friction between receiving and spending money, rather than pushing new products.
- Partnerships with established banks or fintech infrastructure providers can accelerate expansion into neobanking and card services.
- Meeting customers where they are—whether through USSD, WhatsApp, or agent networks—is critical for financial inclusion in regions with diverse digital literacy levels.
- A remittance-led model can serve as a strong foundation for expanding into broader digital financial services, particularly in cross-border markets.
FAQ
What is Mukuru’s core business model?
Mukuru operates as a remittance-led neobank, focusing on cross-border money transfers while expanding into everyday financial services like wallets, cards, and payments.
How is Mukuru expanding its services?
Mukuru is launching physical Visa debit cards linked to its wallet, partnering with Bank Zero to provide banking infrastructure, and migrating 500,000 customers to the new platform.
Why is Mukuru’s partnership with Bank Zero significant?
Bank Zero provides the regulated banking infrastructure needed for Mukuru’s account and card offerings, enabling compliance and scalability in markets like Botswana.
Who is leading Mukuru’s expansion in East Africa?
Juan Seco, Chief Growth Officer and Managing Director for East Africa, joined Mukuru in 2023 and is driving the company’s shift toward broader financial services.
Related on Lazyfounder
Sources
- TechCabal · 2026-10-09
The 20-metre neobank: How Mukuru is solving the gap between receiving cash and spending it
This story is an original summary drafted with AI by Lazyfounder from the reporting listed above and checked by automated validation. Facts are attributed to their original publishers; sections marked as analysis are Lazyfounder's. Where a source is in another language, facts were machine-translated and quotations are reported, not reproduced. Read the original coverage via the links, and see our AI policy and corrections policy.
About the author
Editor, Lazyfounder
Tarun Mottlia edits LazyFounders, covering Indian startups, funding rounds, AI and product launches. Every story on the site is AI-assisted and checked against its cited sources before publication.
More stories by Tarun MottliaGet the LazyFounder Brief
Startup, funding and AI news in a five-minute read. Join the early-access list.