Zepto's FY26 Performance: Revenue Surge & Unit Economics Improvement
Discover Zepto's FY26 performance: a revenue surge, improved unit economics, and strategic focus on density. Learn how the startup is navigating profitability challenges in 2026.
LazyFounders
30 SEC SUMMARY
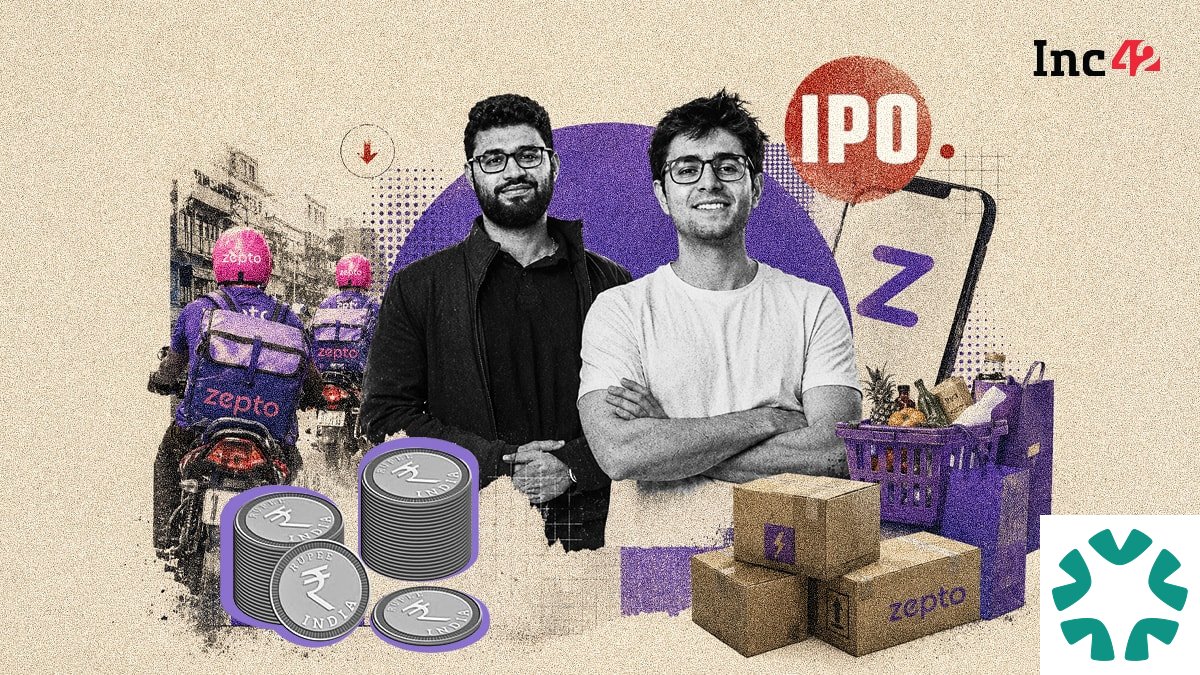
Zepto's FY26 financials reveal a significant revenue surge and improved unit economics, despite ongoing steep losses. The startup doubled its operating revenue and narrowed its adjusted EBITDA loss per order, driven by higher order density and robust advertising revenue. However, profitability remains elusive as Zepto continues to burn cash and faces stiff competition.
TABLE OF CONTENTS
Zepto's FY26 Financial Highlights
Zepto nearly doubled its operating revenue in FY26, climbing to ₹22,624 Cr from ₹11,312 Cr in FY25. Despite this impressive growth, the company's net loss also increased to ₹5,905 Cr from ₹4,697 Cr in the previous year. The company's adjusted EBITDA loss per order improved from ₹136 in FY25 to ₹79 in FY26, and free cash flow burn per order declined from ₹161 to ₹68. These improvements are attributed to higher order density, shorter delivery distances, and the rapid growth of high-margin advertising revenue.
Improved Unit Economics
Zepto's updated draft red herring prospectus (UDRHP) reveals a significant improvement in its per-order economics. Although Zepto continues to lose money on each order, the burn rate has decreased. The startup's adjusted EBITDA loss per order improved from ₹136 in FY25 to ₹79 in FY26. Free cash flow burn per order also declined from ₹161 to ₹68. This improvement is largely due to higher order density across mature markets, which helps in absorbing fixed costs. Additionally, the rapid growth of high-margin revenue streams, particularly advertising revenue, has bolstered Zepto's unit economics.
Zepto’s Biggest Bet Is Density
One of the key strategies Zepto has adopted is building dense clusters of dark stores within existing markets rather than spreading itself thin across new geographies. This approach enables shorter delivery distances, higher order throughput, and lower fulfillment costs. During FY26, Zepto expanded its dark store network to 1,139 stores across India, focusing on increasing store density in urban clusters where demand is strong.
The orders processed per day (OPD) per store increased by 18.1% from 1,325 in FY24 to 1,677 in FY26. More importantly, OPD per store jumped by 50.2% from 1,425 in the quarter ended March 2025 to 2,140 in the quarter ended March 2026. This indicates that Zepto’s stores have become more productive over time. With increased order density, dark stores can process more orders without a proportional increase in operating expenses, leading to improved labor productivity and better infrastructure utilization.
Advertising Emerging As New Growth Lever
Operational efficiency is just one side of the equation. One of the major reasons behind Zepto’s improved unit economics is the emergence of a high-margin revenue business, which is advertising revenue. The startup made ₹1,636 Cr in FY26 ad revenue compared to a mere ₹49 Cr two years ago. Currently, advertising revenue accounts for almost 7.8% of the startup’s overall top line. More than 2,400 brands have tapped into Zepto’s in-house advertising platform.
Unlike the grocery delivery business, advertising is a low-cost but high-margin business. Beyond advertising, Zepto is also generating additional revenue through subscriptions, platform fees, and other ancillary services. Bundled together, these revenue streams are helping Zepto diversify its monetization beyond grocery margins.
The Profitability Debate Is Not Over
Despite the clear improvement in unit economics, Zepto has failed to curtail its losses. The startup reported a free cash flow deficit of ₹4,330 Cr in FY26. Dark store additions, customer acquisition costs, and operational investments continue to drag Zepto’s bottom line. As per its current cash reserves and FY26 cash burn levels, Zepto seems to have a runway of roughly 1.3 years. Zepto is also witnessing a drop in its annual transacting user base. The startup’s UDRHP revealed that its user base declined from 49.54 Mn in the December 2025 quarter to 47.97 Mn in the March 2026 quarter.
Besides, competition remains another major challenge. Eternal-owned BlinkIt continues to remain way ahead of its peers, while Swiggy’s Instamart is trying to scale. Traditional ecommerce players such as Flipkart and Amazon’s entry into the quick commerce space further puts Zepto’s market share under stress. Another point to highlight is that while Zepto is stressing on doubling down on its major revenue-contributing cities, it would also need to spend capital on entering new markets. Now these new stores would take another 12 to 14 months to achieve breakeven, which will further drag down its bottom line.
FAQs
What is Zepto’s strategy for profitability?
Zepto’s strategy revolves around building dense clusters of dark stores within existing markets to improve delivery efficiency and lower per-delivery costs.
How is Zepto diversifying its revenue streams?
Zepto is diversifying its revenue streams through advertising, subscriptions, platform fees, and other ancillary services.
What challenges does Zepto face in achieving profitability?
Zepto faces challenges such as dark store additions, customer acquisition costs, operational investments, competition, and a declining user base.
Conclusion
Zepto’s FY26 performance showcases a significant revenue surge and improved unit economics, driven by higher order density and robust advertising revenue. While the startup is becoming more efficient with each order, profitability remains a distant dream. Zepto’s strategic focus on density and diversification of revenue streams are promising steps, but the company still has a long way to go before achieving profitability.
For more insights, visit blogy.in.
Sources
- inc42.com · 2026-06-10
A Day Late And A Dollar Short: Zepto Fixes Unit Economics, But What About Profitability?
This story is an original summary and analysis written by LazyFounders from the reporting listed above. Facts are attributed to their original publishers; sections marked as analysis are LazyFounders's opinion. Where a source is in another language, facts were machine-translated and quotations are reported, not reproduced. Read the original coverage via the links.